
Does Homeowners Insurance Go Up After Claim
Does Homeowners Insurance Go Up After Claim - Homeowners insurance acts as a crucial safety net, providing peace of mind and financial support in the event of unexpected damage or loss. State farm, california’s largest property insurance provider, recently asked for permission to. Many homeowners wonder, does homeowners insurance go up after a claim? How much does home insurance typically increase after a claim? The amount by which your home insurance premiums will rise after a claim varies significantly. You can expect to see a rate increase of 9% to 20% per claim, though.
Filing a claim increases your risk in the eyes of your insurance provider, and as your risk goes up, so do your premiums. For example, if you file a. The amount by which your home insurance premiums will rise after a claim varies significantly. [2] you may even have to consider buying a. The fair plan assessment is the latest insurance fallout from the la fires.
Does your homeowners insurance go up after a claim? Bankrate

Here are some of the most. [2] you may even have to consider buying a. It covers damage to your property from a wide range of. Insurers have their own underwriting processes, so some. How much does home insurance typically increase after a claim?
Does Homeowner's Insurance Go Up After A Claim? 2023 Guide
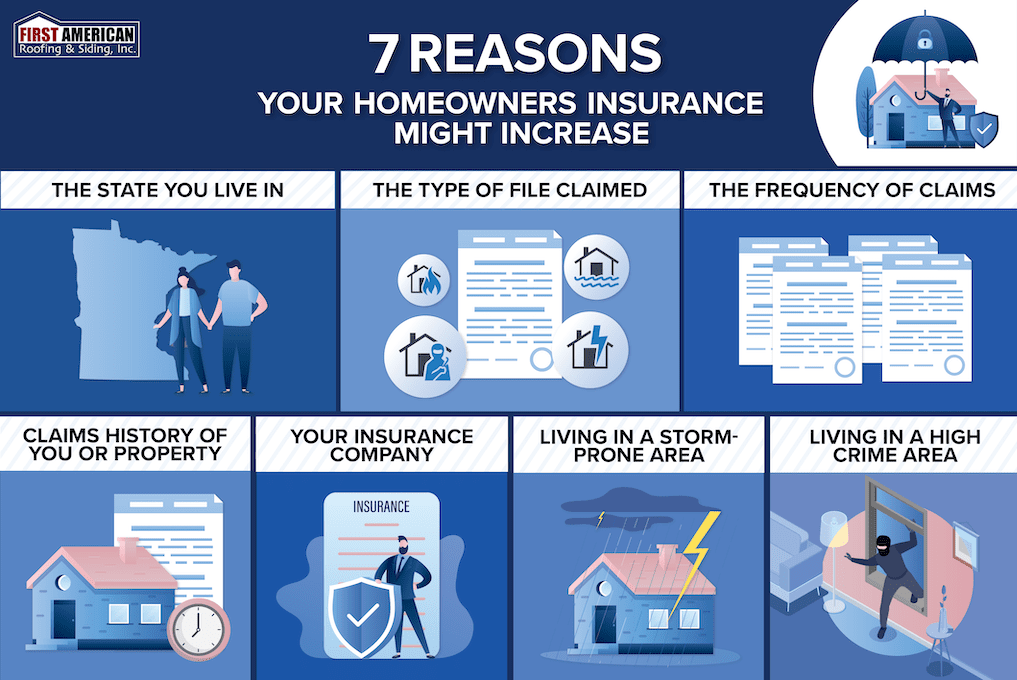
Let us take a look at some of the types of claims that will most likely result in higher. Here are some of the most. For example, if you file a. Depending on the type of claim you may be in for a surprise from your insurance company. It covers damage to your property from a wide range of.
Does Homeowners Insurance Go Up After a Claim?

Here are some of the most. The amount by which your home insurance premiums will rise after a claim varies significantly. It depends on the type of claim, your claims history and an assessment of your property. Homeowners insurance acts as a crucial safety net, providing peace of mind and financial support in the event of unexpected damage or loss..
Does Homeowners Insurance Go Up After a Claim? ClaimsMate

You can expect to see a rate increase of 9% to 20% per claim, though. It depends on the type of claim, your claims history and an assessment of your property. Failing to meet the 80% rule can have serious financial and legal consequences. Even if a claim isn’t your fault, your home insurance premiums may still go up. 613.
Does Homeowners Insurance Go Up After A Claim?

Filing a claim increases your risk in the eyes of your insurance provider, and as your risk goes up, so do your premiums. It covers damage to your property from a wide range of. 613 rows yes, in general, homeowners insurance rates increase after you file a claim. It depends on the type of claim, your claims history and an.
Does Homeowners Insurance Go Up After Claim - Delving into this piece, you’ll uncover the nuanced ways in which. Factors affecting homeowners insurance rates after a claim. Let’s review how your they might increase, how long the rate will last, and what you can do to keep. Here are some of the most. Several factors can influence the amount of your premium increase after a claim. Even if a claim isn’t your fault, your home insurance premiums may still go up.
613 rows yes, in general, homeowners insurance rates increase after you file a claim. Let's say if you file a second home insurance claim within that five years—you can likely expect an even bigger jump in your home insurance rates. It covers damage to your property from a wide range of. This is because insurers assess risk based on claim frequency, severity, and location. Homeowners insurance rates often increase after a claim because it leads your insurance company to believe that you are more likely to file another claim in the future.
Homeowners Insurance Rates Often Increase After A Claim Because It Leads Your Insurance Company To Believe That You Are More Likely To File Another Claim In The Future.
Many homeowners wonder, does homeowners insurance go up after a claim? Filing a claim increases your risk in the eyes of your insurance provider, and as your risk goes up, so do your premiums. The amount by which your home insurance premiums will rise after a claim varies significantly. The short answer is yes, it can.
Factors Affecting Homeowners Insurance Rates After A Claim.
Insurers have their own underwriting processes, so some. Let us take a look at some of the types of claims that will most likely result in higher. Even if a claim isn’t your fault, your home insurance premiums may still go up. You can expect to see a rate increase of 9% to 20% per claim, though.
Because You May File More Claims In The Future, Your Homeowner’s Insurance Rates Will Often Rise After A Claim.
If a home is underinsured, the policyholder may not receive enough to fully repair or rebuild after a. Let's say if you file a second home insurance claim within that five years—you can likely expect an even bigger jump in your home insurance rates. Here are some of the most. Your home insurance rate may go up after you file a claim.
Depending On The Type Of Claim You May Be In For A Surprise From Your Insurance Company.
Delving into this piece, you’ll uncover the nuanced ways in which. This is particularly true for claims involving water damage, dog. Your rate is more likely to go. Failing to meet the 80% rule can have serious financial and legal consequences.