
What Is A Self Insured Retention
What Is A Self Insured Retention - Understanding retention structures is crucial for determining how risks are absorbed and managed. Organizations can use it as a risk management tool to reduce the cost of insurance premiums. A key difference between them is that a deductible reduces the limit of insurance while an sir does not. Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. It’s like a deductible in a conventional insurance policy, except it’s utilized in umbrella coverage. This differs from a deductible in key ways and can significantly impact financial responsibility, claims handling, and overall risk management.
This differs from a deductible in key ways and can significantly impact financial responsibility, claims handling, and overall risk management. Understanding retention structures is crucial for determining how risks are absorbed and managed. Before the insurance policy can take care of any damage, defense or loss, the insured needs to pay this clearly defined amount. Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. In contrast, a deductible policy often requires the insurer to cover your losses immediately, and then collect reimbursement from you afterward.
SelfInsured Retention (SIR) in Construction Insurance Explained Procore

Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. In contrast, a deductible policy often requires the insurer to cover your losses immediately, and then collect reimbursement from you afterward. It’s like a deductible in a conventional insurance policy,.
Deductibles and Self Insured Retention ALIGNED Insurance

What is a self insured retention? This differs from a deductible in key ways and can significantly impact financial responsibility, claims handling, and overall risk management. Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. It’s like a deductible.
Self Insured Retention Policy kenyachambermines
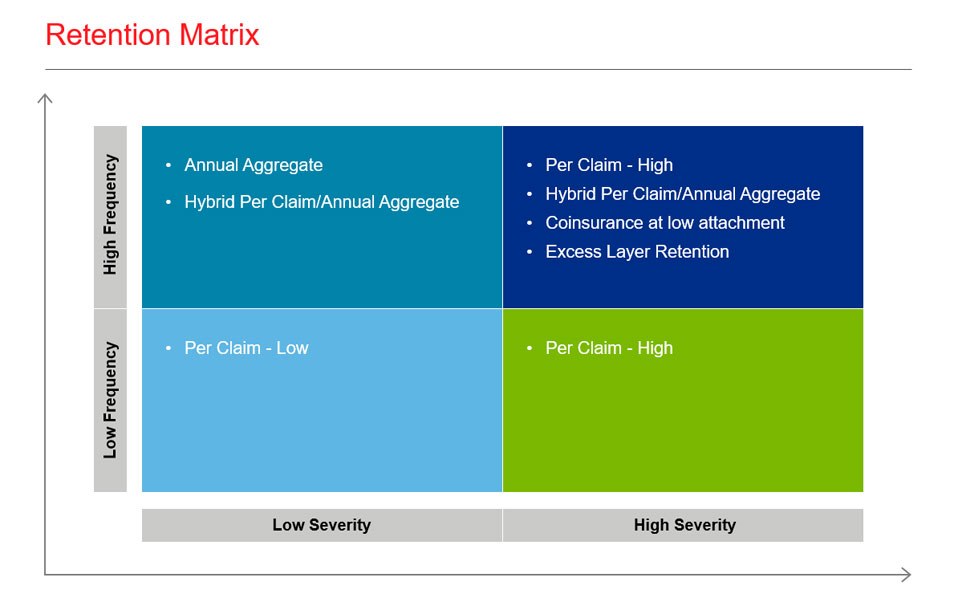
Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. Before the insurance policy can take care of any damage, defense or loss, the insured needs to pay this clearly defined amount. Organizations can use it as a risk management.
SelfInsured Retention vs Deductible What are the Differences?

It’s like a deductible in a conventional insurance policy, except it’s utilized in umbrella coverage. Organizations can use it as a risk management tool to reduce the cost of insurance premiums. In contrast, a deductible policy often requires the insurer to cover your losses immediately, and then collect reimbursement from you afterward. Under a policy written with an sir provision,.
selfinsured retention Archives Redwood Agency Group

What is a self insured retention? A key difference between them is that a deductible reduces the limit of insurance while an sir does not. Before the insurance policy can take care of any damage, defense or loss, the insured needs to pay this clearly defined amount. In contrast, a deductible policy often requires the insurer to cover your losses.
What Is A Self Insured Retention - Before the insurance policy can take care of any damage, defense or loss, the insured needs to pay this clearly defined amount. What is a self insured retention? Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. It’s like a deductible in a conventional insurance policy, except it’s utilized in umbrella coverage. This differs from a deductible in key ways and can significantly impact financial responsibility, claims handling, and overall risk management. A key difference between them is that a deductible reduces the limit of insurance while an sir does not.
Organizations can use it as a risk management tool to reduce the cost of insurance premiums. This differs from a deductible in key ways and can significantly impact financial responsibility, claims handling, and overall risk management. A key difference between them is that a deductible reduces the limit of insurance while an sir does not. In contrast, a deductible policy often requires the insurer to cover your losses immediately, and then collect reimbursement from you afterward. Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached.
What Is A Self Insured Retention?
This differs from a deductible in key ways and can significantly impact financial responsibility, claims handling, and overall risk management. Under a policy written with an sir provision, the insured (rather than the insurer) pays the defense and/or indemnity costs associated with a claim until the sir limit is reached. It’s like a deductible in a conventional insurance policy, except it’s utilized in umbrella coverage. Before the insurance policy can take care of any damage, defense or loss, the insured needs to pay this clearly defined amount.
Organizations Can Use It As A Risk Management Tool To Reduce The Cost Of Insurance Premiums.
A key difference between them is that a deductible reduces the limit of insurance while an sir does not. Understanding retention structures is crucial for determining how risks are absorbed and managed. In contrast, a deductible policy often requires the insurer to cover your losses immediately, and then collect reimbursement from you afterward.